Murray Income Trust
The trust usually pays dividends four times a year, although their frequency and amount are not guaranteed. You can take these dividends as regular income to support your spending or reinvest them and give your money more time to grow.
Upcoming webinar
Artemis is a specialist active investment manager with a strong heritage in income investing. Using disciplined fundamental research and a long-term mindset, the Artemis Income team maintains a focused portfolio of high-quality businesses they believe can deliver high and growing dividends. The team aims to preserve the trust’s AIC Dividend Hero status, earned through more than half a century of increasing annual dividends.
Investments can also fall, so you might not get back all of your money. Historically, however, money invested for more than five years grows more than cash savings.
Seeking durable income
Focused on UK shares

Income + capital growth
Modest use of gearing
Latest insights
Outgoing Murray Income Trust chair, Peter Tait, believes the investment trust industry should do more to reach younger investors.
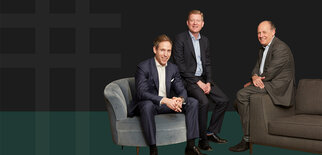
Adrian Frost, Nick Shenton and Andy Marsh reveal what they have learned from decades investing in UK companies.
The team explain their longstanding approach to investing, what they focus on and how they will be managing the Murray Income Trust.
Risk considerations
Market volatility risk
The net asset value of the trust, and the income it receives from its investments, can fall or rise because of movements in stockmarkets, currencies and interest rates, each of which can move irrationally and be affected unpredictably by diverse factors, including political and economic events.
Currency hedging risk
The trust can hedge with the aim of protecting against unwanted changes in foreign exchange rates. The trust is still subject to market risks, may not be completely protected from all currency fluctuations and may not be fully hedged at all times. The transaction costs of hedging, whilst usually minimal, may also negatively impact the trust's returns.
Gearing risk
The trust may borrow to finance further investment (gearing). The use of gearing is likely to lead to volatility in the net asset value meaning that any movement in the value of the trust’s assets will result in a magnified movement in the net asset value.
Income risk
Although the trust aims to pay a high and growing income, the payment of any dividend, and its level, is not guaranteed.
Premium/discount risk
Investment trust shares tend to trade at discounts to their underlying net asset values, although they can also trade at a premium. Discounts and premiums can fluctuate considerably leading to more volatile returns for shareholders. There is no guarantee that the market price of the trust's shares will fully reflect their underlying net asset value.
Market spread risk
As with all stock exchange investments, the prices at which shares can be purchased and sold can be different, this is called the bid-offer spread. The bid-offer spread can widen when trading volumes are lower or when there is increased market volatility.
Risk and reward profile
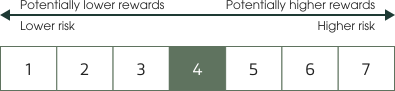
The trust is in the category shown due to historic volatility (how much and how quickly the value of shares in the trust may have risen and fallen in the past due to movements in markets, currencies and interest rates). It may not be a reliable indication of the future risk profile of the trust. The figure highlighted in the risk reward profile is the Summary Risk Indicator (SRI). For more information visit our Glossary of terms.
Our income approach
Learn how our team looks for companies generating high levels of cash that can support sustainable and growing dividends
Advantages of trusts
Investment trusts have special features to help investors, like independent boards of directors and selective use of borrowing
How to invest in Murray
Murray Income Trust can be bought on many online investment platforms, via stockbrokers or with the help of a financial adviser